This article relates to Goal 10: Reduced inequalities, one of the 17 UN Sustainable Development Goals. Goal icon by the United Nations. Emberoot is not affiliated with, or endorsed by, the UN.
Technology can narrow inequality or widen it. Cheap digital payments, open-source identity systems and accessible design have brought services to people who were left out. Biased algorithms, unaffordable data and inaccessible apps can push the same people further out. This article looks at technology and SDG 10 through named, documented examples, and at the limits.
Technology and SDG 10: where tools help
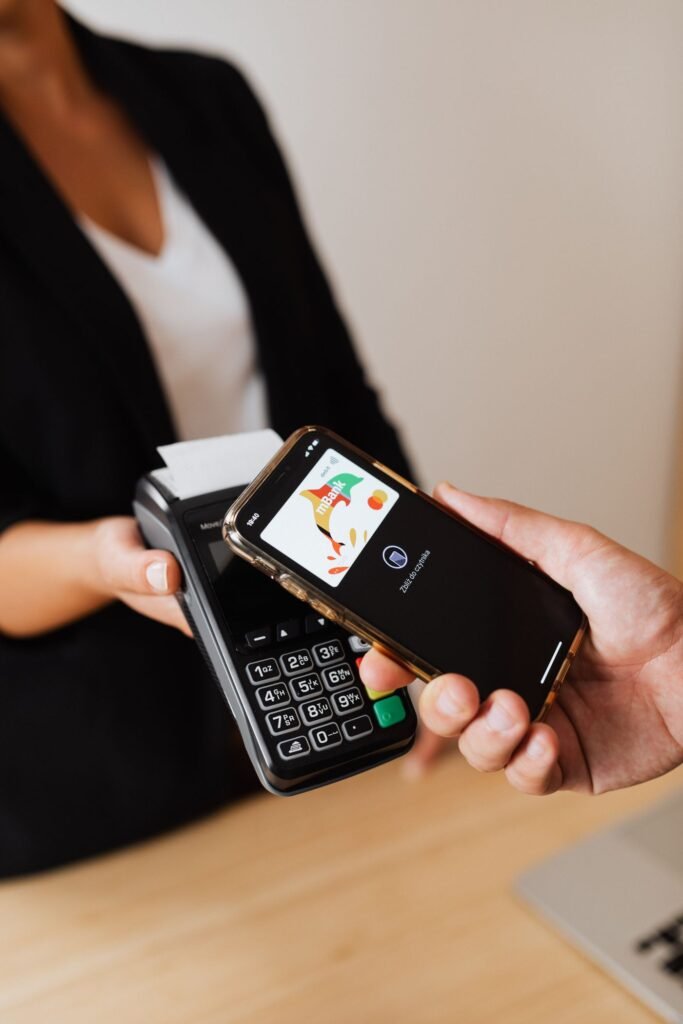
Instant, low-cost payments
India’s Unified Payments Interface handled a record 23.66 billion transactions in July 2026, according to the Government of India, which also cites IMF figures putting UPI at about 49% of the world’s real-time payment volume in 2025. Low-cost, phone-based payments let small traders and low-income households take part in the digital economy, which supports target 10.2 on economic inclusion.
Mojaloop is open-source software for building instant payment systems, published by the Mojaloop Foundation with the stated aim of bringing affordable digital financial services to anyone with a mobile phone. Because it is open source, central banks and payment operators can adapt it without licence fees.
Cheaper remittances
Target 10.c aims to cut the cost of sending money home to below 3%. The World Bank Remittance Prices Worldwide report for Q3 2025 shows why digital matters: digital remittances averaged 4.59%, against 14.99% for banks and a global average of 6.36%. For a migrant sending $200 a month, that difference adds up over a year.
Digital identity people can use
Without an ID, people often cannot open a bank account, enrol in benefits or sign up for a mobile connection. MOSIP, the Modular Open Source Identity Platform incubated at IIIT Bangalore since 2018, gives countries open-source building blocks for national ID systems. It reports 32 country engagements and 14 national rollouts, including work with Ethiopia, Morocco and Sri Lanka.
Accessible design
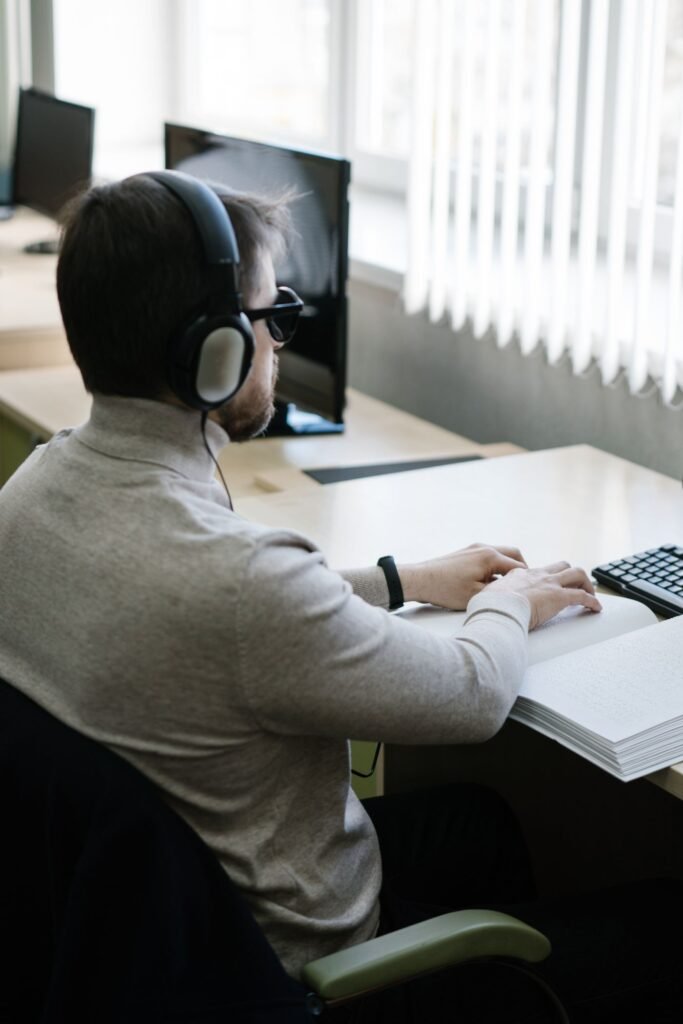
The World Health Organization estimates 1.3 billion people, about 16% of the world’s population, live with significant disability. The WCAG 2.2 guidelines, a W3C Recommendation, explain how to build websites and apps that work with screen readers, keyboard-only use, captions and good colour contrast. Accessibility is one of the cheapest ways a software team can act on SDG 10.
Open data for people left off the map
Many informal settlements and rural areas are missing from official maps, which means they are missed in planning. The Humanitarian OpenStreetMap Team coordinates volunteers who map these places in open data, and works in 94 countries, including on displacement and safe migration.
Data that shows who is left behind
Target 10.2 is hard to track without good data. The UN SDG Report 2026 notes that fewer than half of countries break down their data by income, education or migration status. Simple digital survey tools, open data portals and careful statistical work help governments see which groups are falling behind, so that policies can be aimed where they are needed. The work is mostly unglamorous: consistent definitions, privacy safeguards and publishing results people can check.
Where technology makes inequality worse
Access is the first limit. Digital services help only people who can get online and afford it. Automated decisions are the second. Systems that score credit, screen job applicants or allocate benefits can repeat patterns in past data, so a group that was excluded before stays excluded. Data protection is the third: identity and payment systems hold sensitive data, and weak safeguards hurt the most vulnerable first.
- Test automated decisions for different outcomes by group
- Offer a human route and an appeal for every automated decision
- Design for low bandwidth and basic phones
- Collect only the personal data you need
- Training models only on data from your best customers
- Making an app the only way to get a service
- Ignoring screen reader and keyboard users
- Storing ID numbers without strong security
What this means for product teams
If you are building a fintech, HR, health or public service product, inequality risk is a design question. Check who your product excludes by cost, connection, language, disability or data history, then fix the largest gap first. Our app development and technology advice work includes accessibility and data protection from the first sprint. The SDG 10 goal page lists the targets, and the Global Goals hub links to related goals such as decent work and industry.
Frequently asked questions
How does technology help reduce inequality?
Technology can lower the cost of payments and remittances, give people a usable identity to access services, and make websites and apps usable for people with disabilities. Examples include India’s UPI for instant payments, the open-source MOSIP identity platform and the WCAG 2.2 accessibility guidelines. Each supports specific SDG 10 targets such as 10.2 and 10.c.
Can technology make inequality worse?
Yes. People who cannot afford a phone or data are left out of digital-only services. Automated systems for credit, hiring or benefits can repeat bias in past data. Poorly protected identity and payment data can expose vulnerable people to fraud. Good design includes human review, appeals, offline routes and strong data protection.
Why are digital remittances cheaper?
The World Bank tracks digital and non-digital services separately. In the third quarter of 2025, digital remittances averaged 4.59% of the amount sent, against 14.99% for banks and 6.36% overall. Comparing providers before sending is the simplest way to pay less. The SDG 10 target is to bring average costs below 3% by 2030.